Back to September 2026 Industry Update
September 2026 Industry Update: Truckload Rates
Main Takeaways
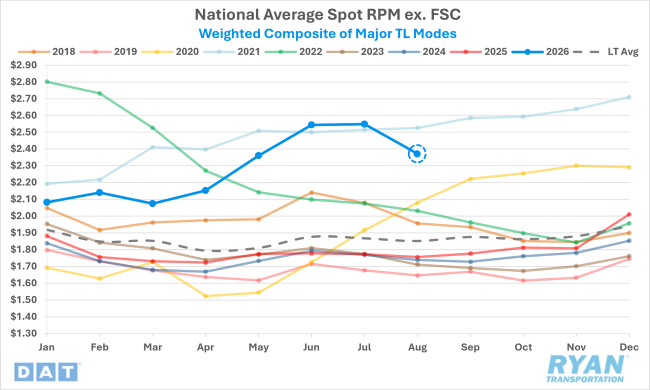
- Spot rates declined sharply from their summer highs in August as market conditions began to normalize during the post-summer slowdown.
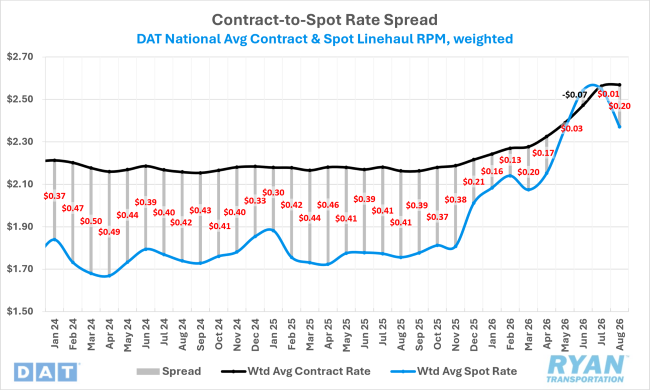
- Contract rates continued to climb to catch up with peak-season spot-rate gains, returning to trend at a premium relative to transactional market pricing.
Summary
Truckload rates remained elevated in August, though pricing momentum moderated as peak-season volatility eased and capacity conditions gradually loosened. Improved routing guide compliance drove steep declines in spot rates, while contract rates climbed further to catch up with the gains seen in transactional pricing earlier in the year. Despite the pullback, both spot and contract rates remained well above year-ago levels as historically tight capacity levels continue to outpace ongoing weakness in demand.
DAT National Average Spot Rates excl. FSC, Weighted Composite Index
Key Points
- Total average truckload spot linehaul rates fell sharply in August, down 6.9% MoM ($0.18) after four straight months of gains.
- Compared to August 2025, total truckload spot rates excluding fuel are up 35.0% ($0.62) YoY and are 27.1% above the long-term average.
DAT National Average RPM Contract vs. Spot
Key Points
- Initially reported total truckload contract linehaul rates increased slightly by just 0.3% (~$0.01) in August and remain 18.8% ($0.41) higher YoY.
- The contract rate premium widened significantly in August, with contract rates trending 8.4% higher than spot rates, up sharply from the 0.5% premium recorded in July.
FTR Total Truck Rate & Outlook
Key Points
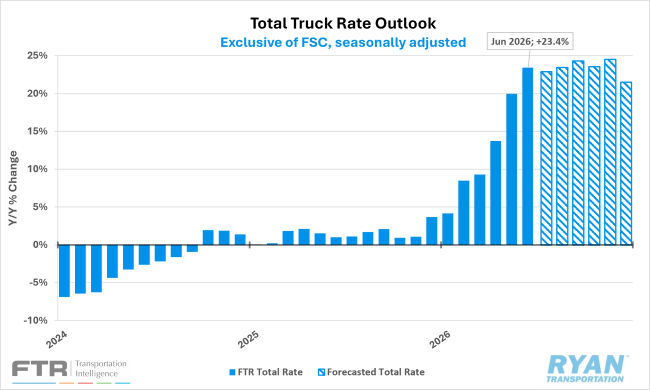
- FTR’s total truckload rate forecast for 2026 was unchanged from the prior growth outlook of +18.3% YoY, as slightly stronger dry van rates offset marginally softer outlooks for flatbed and specialized rates.
- Spot rate growth was slightly weaker in the 2026 outlook, registering +35.8% YoY, down 0.3 percentage points from the previous outlook of +36.1%, while the total truckload contract rate outlook was essentially unchanged at +10.0% YoY, just a tenth of a point higher than prior estimates.
- By equipment type, revised flatbed and dry van rate growth projections were both +18.9% YoY for the 2026 outlook (up from the previous forecast of +18.3% and +18.6%, respectively), while the refrigerated rate outlook remained the same at +17.3% YoY growth.
DAT Fuel Trends
Key Points
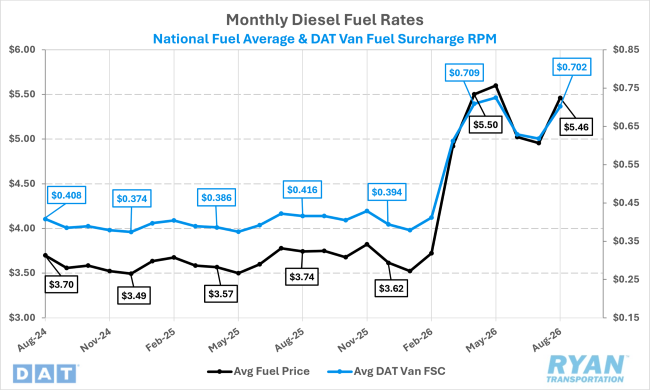
- After two months of declines totaling more than $0.64, the national monthly average price of diesel rebounded in August, jumping nearly $0.51 MoM to $5.46/gallon and remaining well above year-ago levels by $1.72/gallon.
- In its latest Short-Term Energy Outlook (STEO), the Energy Information Administration (EIA) forecasts that distillate fuel oil inventories — what diesel is produced from — will fall below the five-year low in September and remain there through the remainder of 2026 and most of 2027.
- Expectations of prolonged lower global diesel inventories led the EIA to revise its pricing forecast up for 2026 from $4.85/gallon to $5.07/gallon and for 2027 from $4.07/gallon to $4.40/gallon.
Outlook
Looking ahead, truckload rates are expected to remain relatively firm through the remainder of the year and into 2027, supported by capacity conditions; while improving temporarily, they remain tighter than historical norms. Spot rates should ease in the near term as shippers build up inventories run down during the peak summer shipping season ahead of retail shipping ramping up for the holidays in Q4. However, persistent supply constraints, which continue to dominate the market, are likely to limit rate relief as the market searches for its peak-season floor.